
First Home Buyer Tips: A Practical Guide to Buying Your First Home in Queensland
First Home Buyer Tips for Buying with Confidence
Buying your first property is a major milestone. It is natural to feel excited cautious and perhaps a little unsure about where to begin. The good news is that you do not need to know everything on day one. A clear plan realistic budget and the right professional support can make the journey much easier.
- Secure your financial early
Before you spend too much time attending inspections, speak with a lender or qualified mortgage broker and understand your borrowing position. Loan pre-approval can help you set a realistic price range and show vendors that you are a serious buyer. ASIC MoneySmart notes that pre-approval commonly lasts three to six months, although the exact timeframe and conditions depend on the lender. It is not a final loan approval. So your finance still needs to be confirmed for the specific property and transaction.
Your deposit is only one part of the budget. Allow for conveyancing, building and pest inspections, loan and lender costs, insurance moving expenses, adjustments at settlement and any immediate repairs or improvements. If you are buying an apartment or townhouse, remember to investigate body corporate levies and planned special levies as well.
It is also worth stress-testing your budget. Consider how payments would feel if interest rates, utilities, insurance premiums or everyday costs increased. A home should support your lifestyle rather than leave you with no breathing room.
Check Available government assistance
Queensland first-home buyers may be eligible for different forms of assistance, depending on whether they are buying an established home, a new home or vacant land. Current Queensland Government guidance distinguishes between transfer-duty concessions and the First Home Owner Grant. Eligible buyers of a new home may be able to claim a full transfer-duty concession where the relevant contract was signed on or after May 1st 2025. The Queensland First Home Owner Grant is separate and may provide up to $30,000 for an eligible new home valued below $750,000.
Rules, threshold and eligibility requirements can change. Check the official Queensland Government information before relying on any grant or concession and ask your lender, conveyancer or accountant how the rules may apply to your circumstances.
- Research your target area
A property can look perfect online, but the surrounding suburb will shape your daily life. Research more than the listing photos. Visit the area at different times of day and, if possible, on both weekdays and weekends. Pay attention to traffic, noise, parking, walkability, public transport, nearby shops, schools, parks and access to work or family.
Look at recent comparable sales rather than relying only on an advertised price guide. Comparing properties with similar land size, accommodation, condition and location can help you understand whether a home is priced realistically. Your local property professional can also help you interpret the differences between recent sales and the property you are considering.
For Sunshine Coast buyers, it may also be useful to think about lifestyle priorities such as beach access, flood or bushfire exposure, commuting routes, future infrastructure and the practical cost of maintaining a coastal property. Planned transport, school or development projects may influence an area, but they should be researched through reliable sources rather than treated as a guarantee of future price growth.
- Assess your needs realistically
Your first home does not need to be your forever home. Begin with a clear distinction between your essential requirements and your preferences. For example, an extra bedroom, secure parking, a home office, a low-maintenance yard or proximity to public transport may be important for your current lifestyle. A particular kitchen finish or cosmetic style may be easier to change later.
Think about how the home will work in two or five years, not only on inspection day. Consider storage, natural light, privacy, ventilation, outdoor space access and the likely cost of making changes. If you are buying with a partner, discuss your non-negotiables before you start making offers.
Be careful not to stretch your budget simply because a property feels emotionally right. A well located, sound and manageable home may be a better first step than a larger property that creates ongoing financial pressure.
-
Take a long-term view and complete your due diligence
Property decisions should be based on evidence, not urgency. A slower market can create opportunities to negotiate, while a competitive market can make it tempting to overlook important checks. In either situation, take the time to understand what you are buying.
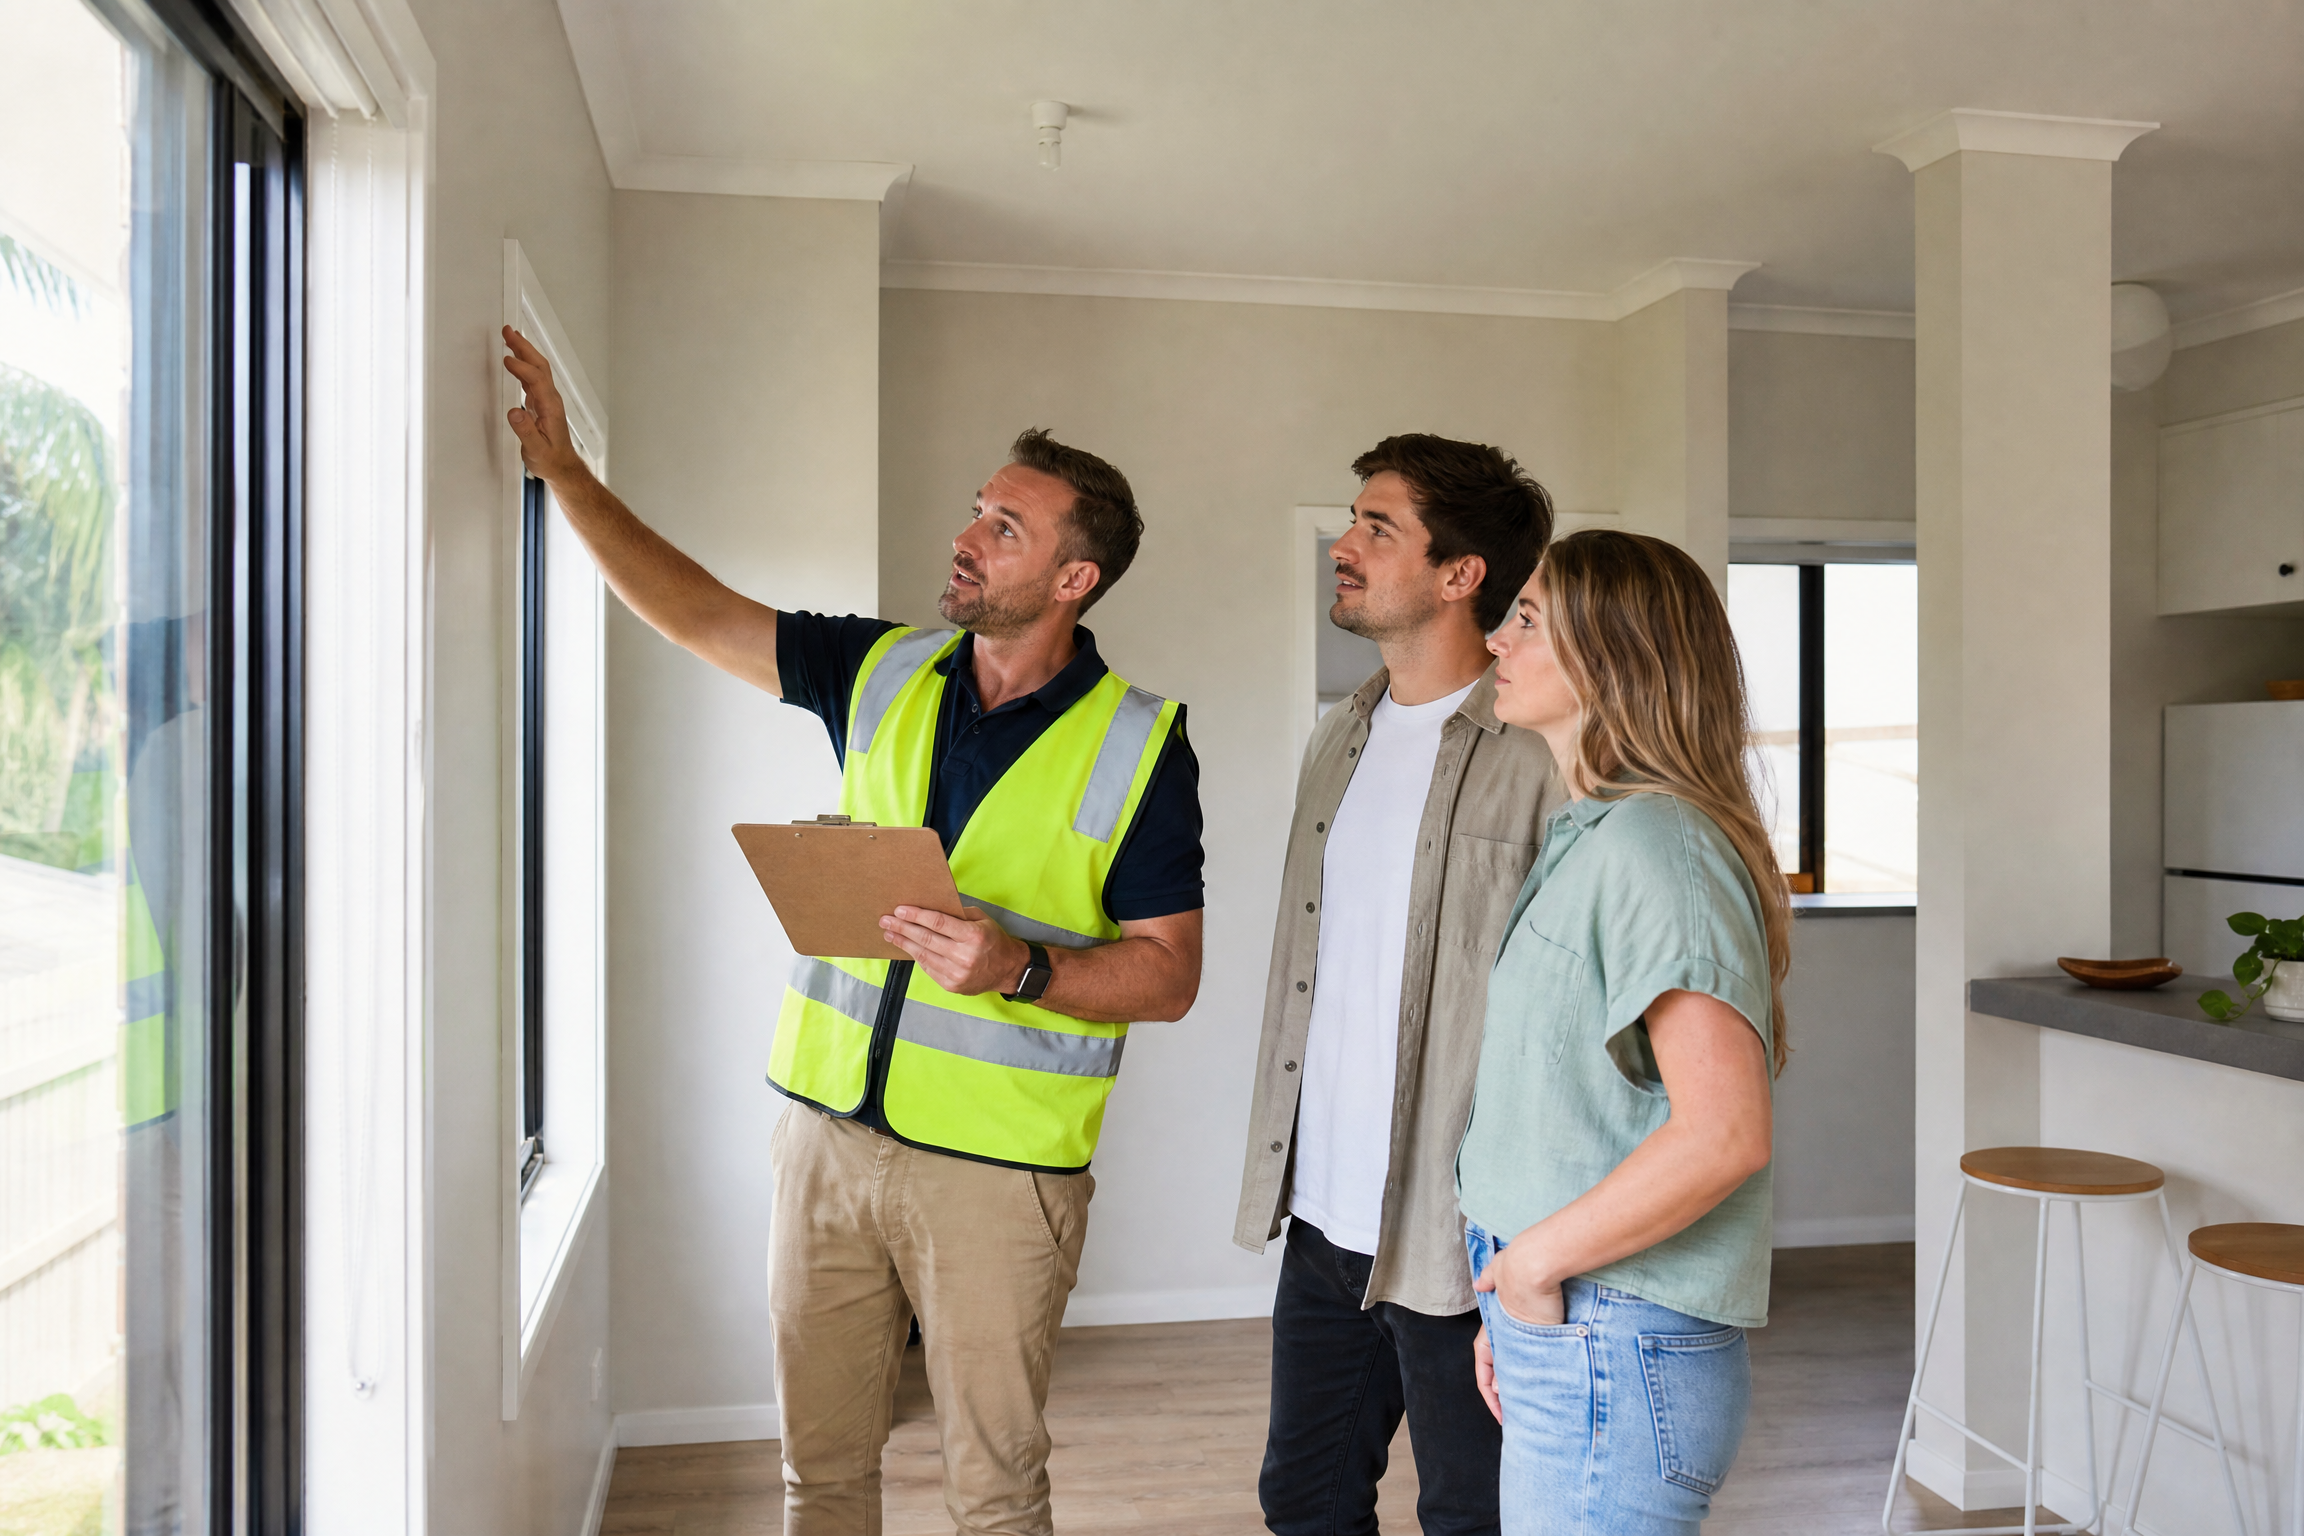
Arrange independent building and pest inspections where appropriate. Read the inspection report carefully and ask questions about defects, moisture, termites, drainage, roof condition and any recommended works. For apartments and townhouses, review body corporate records, budgets, insurance, meeting minutes and any proposed capital works.
Before signing, have a solicitor or conveyancer review the contract and explain the conditions, settlement date, inclusions, exclusions and any special terms. MoneySmart recommends getting professional legal help with the contract because it can help prevent costly mistakes.
If the property needs renovating, prepare a realistic scope and budget rather than assuming the work will be inexpensive. A renovation can add comfort and functionality, but it is not a guaranteed way to create a profit. The same principle applies if you may sell later: future market conditions cannot be predicated with certainty.
- Consider the future carefully, including investment potential
If you have a plan to potentially rent out the property in the future, investigate the fundamentals before you buy. Consider the likely tenant profile, local employment, transport, amenities, vacancy conditions, ongoing maintenance and the costs of managing the property. Obtain independent advice about tax, finance and landlord obligations.
Historical growth is not a promise of future performance. Instead of choosing a suburb solely because it has been described as a “growing area”, consider whether the property is suitable for your budget, lifestyle and long-term plans. A property that is easy to maintain and well connected to essential amenities may offer greater practical flexibility than one chosen only for a speculative outlook.
Your first home can be a valuable foundation, whether you live in it for many years, renovate gradually or eventually move on. The right decision is the one that fits your circumstances and remains manageable through changing market conditions.
A simple first-home-buyer checklist
Ready to take the next step?
The first-home-buyer process becomes much easier when you have local guidance and a clear plan. At Fulton and Co Property, we can help you understand the local market, compare suitable properties and approach your search with practical, honest advice.
If you are looking for your first home on the Sunshine Coast or want to understand what is currently available, contact Fulton and Co Property or book a consultation.
Important note: This article is general information only and is not financial, legal, tax or lending advice. Government schemes, lending rules, property values and market conditions can change. Confirm your eligibility and obtain advice from appropriate qualified professionals before making a property decision.